★★★★★
Denise Rock
a month ago
Excellent experience selling our home.
Short answer: A VA loan realtor in Richmond is a real estate agent who understands the VA home loan and builds your purchase around it. At The Hogan Group Real Estate, that is the work we do. We are one of Central Virginia's leading real estate teams by units sold and volume, and we help veterans and military buyers use their VA benefit across the Richmond region with zero down and no private mortgage insurance.
A VA loan is one of the strongest tools a buyer can bring, and it works best when the VA loan realtor beside you knows it well. We pair the reach of a busy team with hands-on fluency in VA financing, so your VA benefit reads as an advantage rather than a detail that worries sellers. Most veterans want a VA loan realtor who stays ahead of the paperwork.
A VA loan realtor runs the purchase around the loan from the first conversation. We connect you with VA-experienced mortgage lenders and get you fully pre-approved, so your Certificate of Eligibility, entitlement, and funding fee are clear before we write an offer. Once we start touring, we read each property through the VA lens and flag condition issues that could trip the VA appraisal and its Minimum Property Requirements.
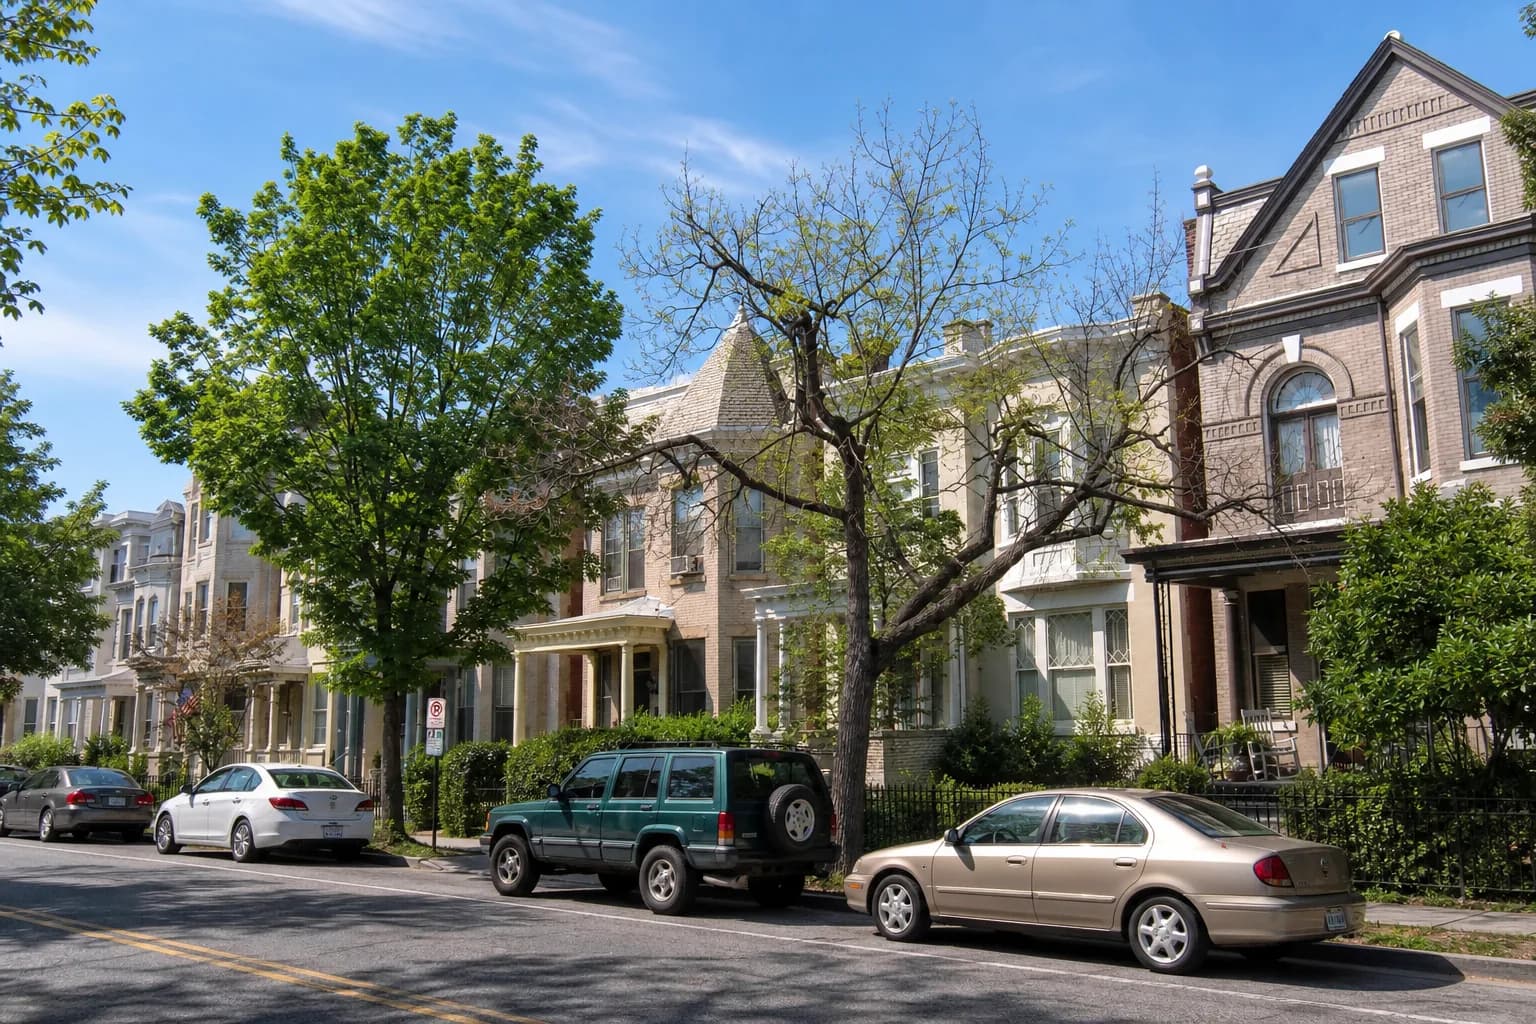
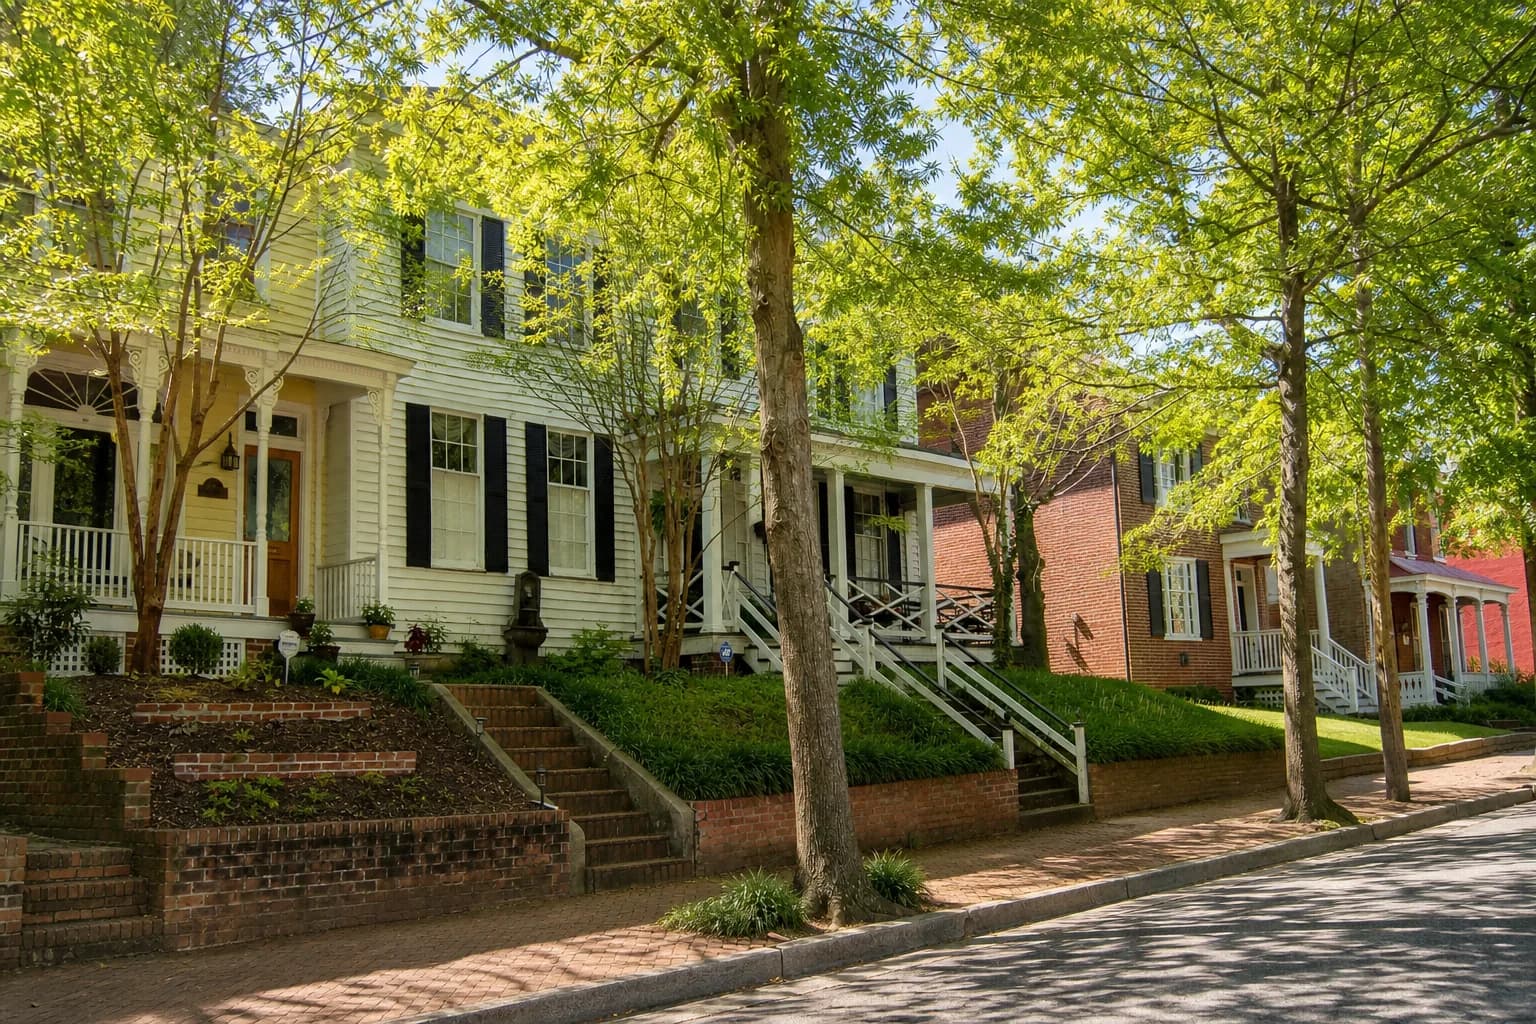
Not every VA loan realtor in Richmond reads a home the way a VA buyer needs. Before a showing, we study the listing imagery and property records, so your touring time goes toward homes that fit your life and the loan.
| What we do | Why it protects your VA benefit |
|---|---|
| Connect you with VA-fluent loan officers | Clean pre-approval and entitlement up front |
| Read listing photos and tour with a VA eye | Catch repairs before the appraisal does |
| Structure and present the offer | Listing agents see a strong, qualified buyer |
| Negotiate appraisal, funding fee, closing costs | More of your money stays in your pocket |
We suggest ordering your Certificate of Eligibility the same week you reach out. It costs nothing and shows how much entitlement we have. From there, most clients are touring within a couple of weeks.
This is for active-duty service members, veterans, and military families buying around Richmond. Some are first-time buyers. Others relocate on PCS orders and need to move quickly from a distance. If you have earned the VA loan and want a VA loan realtor who treats it as the asset it is, this is for you. For relocating buyers, we handle local legwork so distance does not cost you the house.
The question most buyers ask is how the VA loan compares with a conventional one. For many eligible buyers, the VA loan wins on upfront cost: zero down and no monthly mortgage insurance, traded against a one-time funding fee. Here is how we lay it out.
| Factor | VA loan | Conventional loan |
|---|---|---|
| Down payment | As low as 0% | Often 3% to 20% |
| Mortgage insurance | None | Usually required under 20% down |
| Funding fee | Yes (waived for many disabled veterans) | No funding fee |
| Property standards | VA appraisal and MPRs | Standard appraisal |
| Who qualifies | Veterans, service members, some spouses | Most buyers with credit |
Some buyers do not realize the funding fee can be rolled into the loan, or that a service-connected disability rating can waive it entirely. That one detail changes the math on closing costs, which is why we confirm it early.
Our record is the volume of homes we have helped Central Virginia families buy and sell. Read our 5-star reviews and a pattern shows up: clients keep choosing and referring us. For a VA buyer, we have guided enough VA loan purchases to know where they stall.
What a high-volume, VA-focused team brings
What to weigh
The one we hear most is that sellers shy away from VA offers. Handling that is much of what we do. We present and negotiate your offer so it competes on strength. When clients ask whether the VA appraisal will slow things down, we spot likely issues early and build the timeline around them. For Richmond buyers new to the VA benefit, terms like funding fee and entitlement can feel unfamiliar, so we explain each step in plain language.
Reach out and tell us where you are stationed or headed. From there, we connect you with a VA-experienced lender for pre-approval. Once that is in hand, we start touring homes we have already vetted for the VA appraisal, which is how most clients find the right one faster. Reach us at our Richmond office, 2120 Staples Mill Rd, or call (804) 571-2900.
Showing 2 of 521 reviews. Rating and total above cover all reviews.
Excellent experience selling our home.
I had a fantastic experience working with the agent Austin and The Hogan Group.
Is it harder to buy a home with a VA loan in Richmond?
Not with the right VA loan realtor. The VA loan adds steps like the appraisal and MPRs, though we build the process around them so your purchase moves as smoothly as any other.
Do sellers in Virginia really avoid VA buyers?
Some worry about it, and that worry usually comes from how the offer is presented. We package your offer so listing agents read it as strong and well-qualified.
What does the VA funding fee cost?
It varies by down payment and whether it is your first use, and it can often be rolled into the loan. Many veterans with a service-connected disability pay nothing.
Can you help if I am relocating from another part of Virginia?
Yes. We handle property research, inspections, and local coordination so you can buy from a distance confidently.
The Hogan Group's buyer representation is built for this. Let our VA-focused agents guide your Richmond purchase from pre-approval through closing. Call (804) 571-2900 or visit our Staples Mill Road office.